From Blueprint to Move-In: Understanding Construction Loans Made Easy
Learn everything about From Blueprint to Move-In: Understanding Construction Loans Made Easy, including loan types, application tips, and choosing the right hard money lender for your construction journey.
Introduction
Building your dream home is one of the most exciting ventures you'll ever undertake. But funding it? That can feel like decoding a mystery. From blueprint to move-in, understanding construction loans doesn’t have to be complicated. With the right lender, proper planning, and smart decision-making, your dream can become a solid reality—brick by brick.
Whether you're constructing a custom home from the ground up or doing a major renovation, construction loans are essential tools that offer financial support through every phase of your project. Let’s break down the process in simple terms, so you can build confidently and avoid the headaches many first-timers face.
What Are Construction Loans?
Understanding the Basics of Construction Loans
A construction loan is a short-term, high-interest loan used to finance the cost of building a home or property. Unlike traditional mortgages that disburse a lump sum at closing, construction loans release funds in stages, aligned with each phase of the construction process.
This type of loan is crucial because most traditional banks won’t finance a property that doesn’t yet exist. Builders and owners use construction loans to cover labor, materials, permits, and land costs.
Types of Construction Loans Explained
- Construction-to-Permanent Loans: These loans convert into a standard mortgage after construction.
- Stand-Alone Construction Loans: Requires you to apply for a separate mortgage after the home is completed.
- Owner-Builder Construction Loans: For those acting as their own general contractor.
- Renovation Loans: Used for extensive home renovations or expansions.
Each loan type has its own features and is suited to different borrower needs.
How Do Construction Loans Work?
Stages of Construction Financing
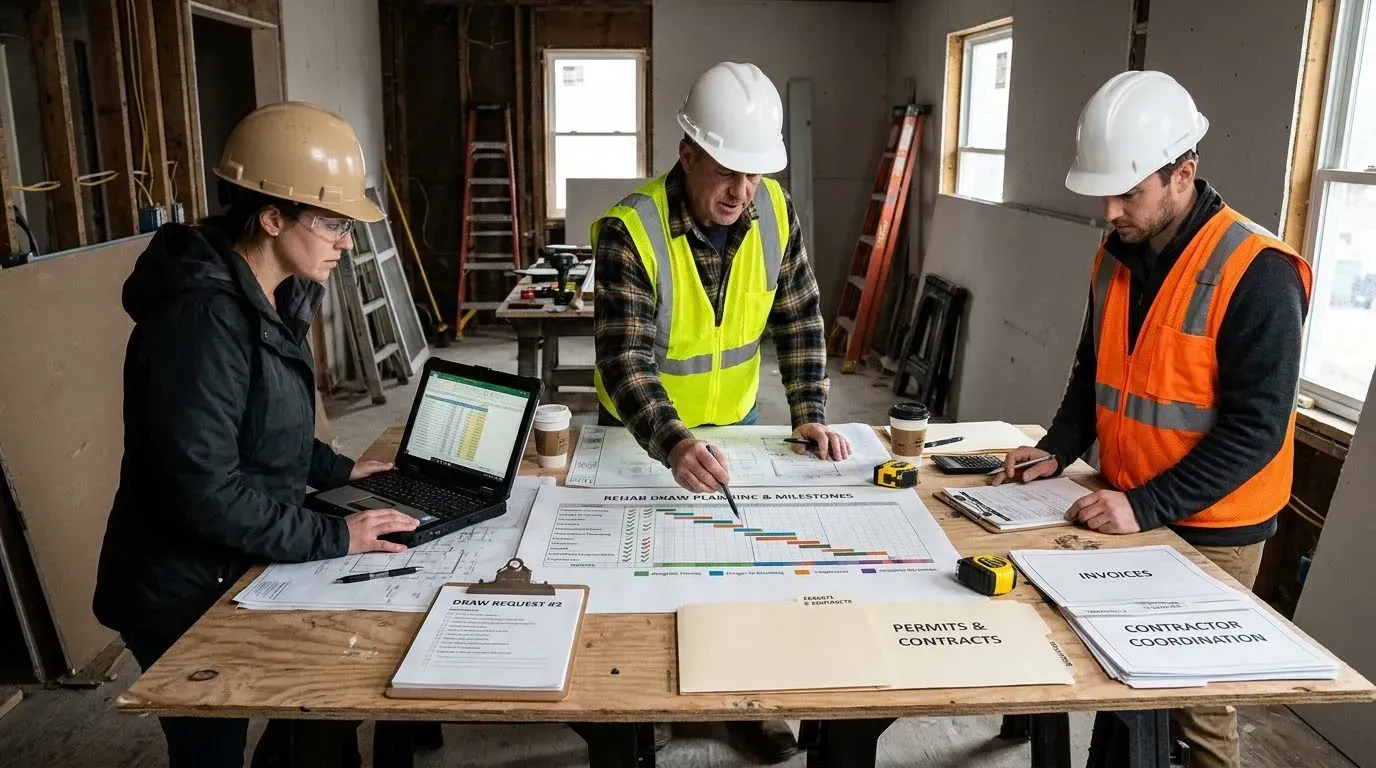
Construction loans are structured around a draw schedule. Funds are released in "draws" at various project milestones:
- Foundation
- Framing
- Roofing
- Electrical/Plumbing
- Final touches
Lenders often send inspectors to verify progress before releasing the next installment.
The Role of the Lender in Your Build Journey
Lenders act as your financial partner. They monitor your project, manage fund disbursements, and keep tabs on the timeline and budget. Working with a reliable Hard Money Lender ensures smoother processing, flexibility, and quicker approvals.
Blueprint to Move-In: The Construction Loan Timeline
Pre-Approval and Planning Phase
Before breaking ground, you need to be pre-approved. This includes submitting financial documents, blueprints, building permits, and contractor bids. A clear project plan can make or break your approval chances.
Construction Phase and Draw Process
During the construction phase, your contractor submits draw requests for completed stages. You must track expenses closely, manage the timeline, and communicate any changes with your lender.
Final Inspection and Conversion to Mortgage
Once the home is complete, an inspection ensures everything meets code. If you have a construction-to-permanent loan, it automatically converts to a mortgage. Otherwise, you'll need a new loan to pay off the original one.
Key Features of Construction Loans
Interest-Only Payments During Construction
You usually only pay the interest on the disbursed amount during construction. This helps ease cash flow during the building process.
Short-Term vs. Long-Term Loans
Most construction loans last 6 to 18 months. After that, you either convert or refinance into a traditional mortgage.
Variable vs. Fixed Rate Options
Construction loans often have variable rates based on prime interest. However, fixed options exist, especially when you lock in during the mortgage phase.
Requirements for Getting a Construction Loan
Credit Score and Financial Health
Most lenders require a minimum credit score of 680, though hard money lenders can be more flexible. Steady income and a low debt-to-income ratio also help.
Down Payment and Equity Considerations
Expect to pay 20% to 25% down. Some lenders allow you to use land equity as your down payment.
Contractor Approval and Project Plans
You’ll need to hire a licensed contractor and provide blueprints, detailed budgets, and timelines for approval.
Construction Loan vs. Mortgage: What’s the Difference?
Comparing Financing Structures
A mortgage gives you a lump sum, while a construction loan pays in stages. Mortgages are for completed homes, while construction loans cover projects in progress.
Which One is Right for You?
If you're buying an existing home—go with a mortgage. Building from scratch? A construction loan is your best option, especially with a trusted Hard Money Lender.
Choosing the Right Hard Money Lender
Why a Hard Money Lender Might Be the Best Option
Hard money lenders offer quicker approvals, flexible terms, and fewer hoops to jump through—perfect for those with unique projects or less-than-perfect credit.
Hard Money Lender You Can Trust
Go with a lender who knows the local market, offers personalized terms, and understands construction timelines. Choosing the right partner can be the difference between success and stress.
How to Apply for a Construction Loan
Steps to Apply
- Get pre-qualified
- Submit architectural plans and budgets
- Provide income and credit documentation
- Choose a contractor
- Secure loan approval
Documentation You’ll Need
- Blueprints and permits
- Personal financial documents
- Contractor agreement
- Property deed or purchase contract
Common Mistakes to Avoid with Construction Loans
Misjudging the Budget
Always include a buffer of at least 10–15% for unexpected expenses. Material costs and labor rates fluctuate.
Not Vetting Your Contractor
A bad contractor can derail your entire project. Check references, license, and past work before hiring.
Tips for First-Time Homebuilders
Setting Realistic Expectations
Things rarely go 100% as planned. Expect delays, cost overruns, and weather issues. Flexibility is key.
Working with an Experienced Team
Surround yourself with professionals—architects, contractors, and lenders who specialize in construction loans.
Managing Your Construction Loan Wisely
Monitoring Draw Schedules and Timelines
Stay engaged in every step. Review draw schedules and confirm work before allowing disbursements.
Communicating with Your Lender Regularly
Transparency with your lender builds trust and helps resolve issues faster. Schedule check-ins to stay aligned.
From Blueprint to Move-In: The Final Checklist
Inspection and Appraisal Process
Your lender will schedule a final inspection and appraisal to ensure the home is move-in ready and valued correctly.
Occupancy Certificate and Loan Closure
Once you pass the inspection, you’ll get your occupancy certificate. Now it’s time to move in and celebrate!
FAQs About Construction Loans
What credit score is needed for a construction loan?
Most lenders prefer 680+, but
hard money lenders may accept lower scores with proper documentation.
Can I build my own home without a contractor?
Yes, through an owner-builder loan—but lenders scrutinize experience and project plans closely.
Are construction loans more expensive than mortgages?
Yes, they typically have higher interest rates due to increased risk.
How long does construction loan approval take?
Approval can take 30–45 days, depending on documentation and lender policies.
Do I need to own the land before getting a loan?
Not necessarily. You can use the loan to purchase land, but it affects your loan terms.
What happens if construction takes longer than expected?
You may need an extension or face additional fees, depending on your lender’s policy.
Need Help? Contact a Professional
Have more questions or need expert guidance? Reach out to a trusted team at Contact and get personalized help with your construction loan needs.
Conclusion
From blueprint to move-in, construction loans are the financial scaffolding that supports your dream home journey. With careful planning, the right Hard Money Lender, and a committed team, the process becomes not only manageable but exciting.
Don’t let the financing scare you off. Understand the loan. Own the process. Build your dream.
Links