Strategic Financing: Securing a Rental Property Loan for East Los Angeles Real Estate
Acquiring income-producing properties requires more than just a sharp eye for market trends. It demands highly structured capital. Investors seeking to build sustainable wealth rely on targeted financial instruments to acquire, stabilize, and scale their portfolios. Finding the right financing partner provides the leverage necessary to turn an ambitious property vision into a tangible, cash-flowing asset.
At GRO Los Angeles Hard Money Real Estate, we provide investors with the capital they need to execute their strategies. Headquartered right here in East Los Angeles, CA, we understand the distinct rhythms of the local market. By aligning sophisticated lending products with regional insights, investors can systematically expand their holdings while mitigating exposure to risk.
Navigating the Real Estate Market in East Los Angeles
East Los Angeles represents a dynamic environment for property investors. The region offers a compelling mix of established neighborhoods, robust tenant demand, and continuous urban revitalization. Proximity to major employment hubs and essential transit corridors makes this area highly attractive to long-term renters.
Investing in this specific pocket of Southern California requires nuanced local knowledge. Properties in East LA range from historic single-family homes to mid-sized multi-family complexes. Each property type presents a different cash flow profile and demographic appeal. The tenant base is incredibly stable, often resulting in lower turnover rates for landlords who maintain their properties well.
As gentrification and urban renewal projects push outward from downtown Los Angeles, East LA continues to see property appreciation alongside rising rental rates. This dual benefit of immediate monthly cash flow and long-term equity growth creates a highly favorable environment for capital deployment. To learn more about how our firm is positioned to help you capitalize on these local dynamics, you can read about our core mission and background.
Core Mechanics of a Rental Property Loan
Financing an investment property operates on fundamentally different principles than securing a mortgage for a primary residence. When underwriting a primary home, institutions focus almost entirely on the personal income and debt-to-income ratio of the applicant. In the investment sector, lenders pivot their focus toward the performance metrics of the asset itself.
A dedicated rental property loan is designed specifically for non-owner-occupied real estate. The primary consideration for underwriting these loans is the property capacity to generate consistent revenue. Lenders evaluate the gross monthly rent, vacancy projections, operating expenses, and property taxes to determine the viability of the investment.
Because investment properties inherently carry slightly different risk profiles than primary homes, the structures of these loans reflect that reality. Borrowers should anticipate higher down payment requirements, typically ranging from twenty to thirty percent of the purchase price. This equity buffer protects the lender while ensuring the borrower has significant capital committed to the project. Interest rates may also reflect a slight premium over conventional owner-occupied mortgages. However, professional investors understand that the cost of capital is simply a line item in a broader profitability calculation. The ability to leverage borrowed funds to control a high-value asset far outweighs the incremental cost of interest.
Exploring Diverse Real Estate Financing Options
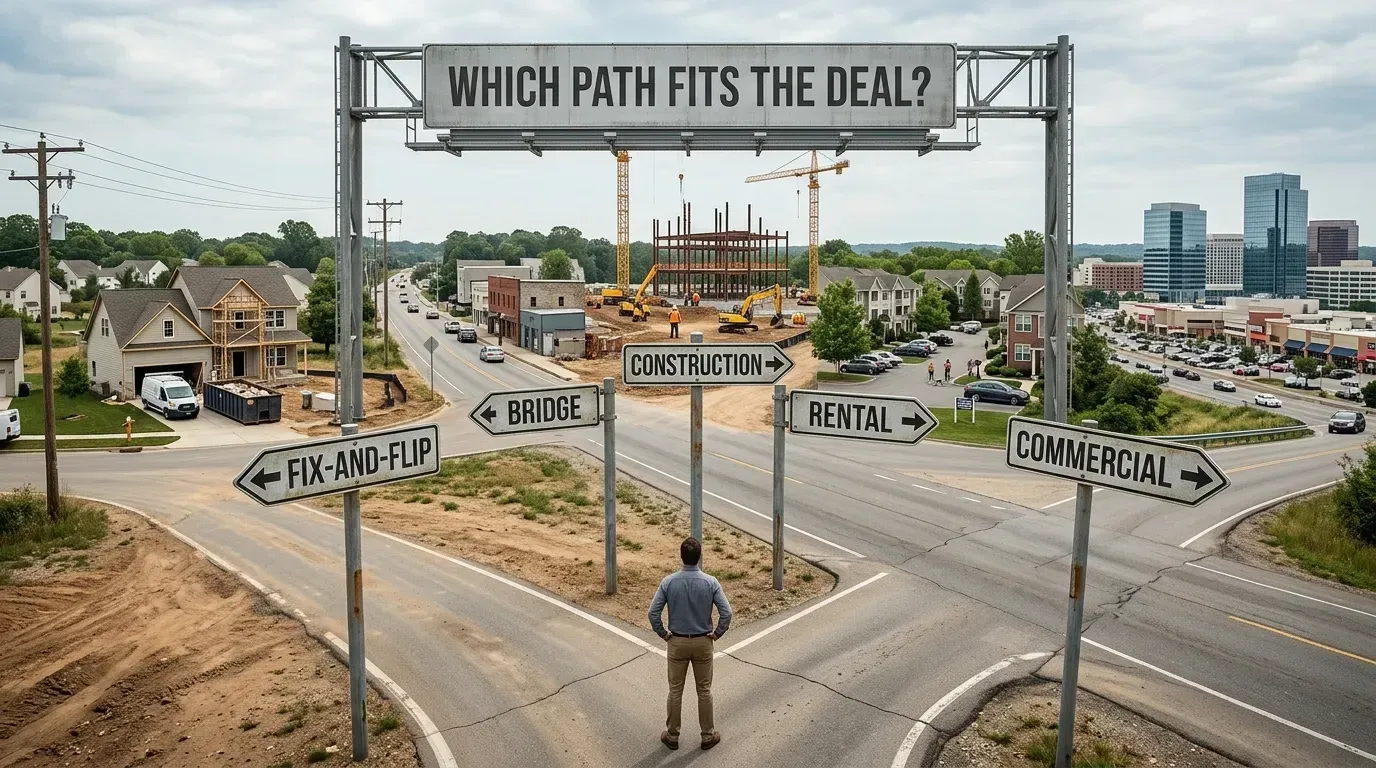
The capital markets offer several distinct pathways for financing income properties. Selecting the correct product depends entirely on the investor timeline, the condition of the property, and the overarching strategy for the asset.
Debt Service Coverage Ratio Mortgages
One of the most efficient tools for active investors is the Debt Service Coverage Ratio or DSCR loans program. This loan bypasses the traditional requirement for personal income verification. Lenders do not request W-2s, tax returns, or personal pay stubs. Instead, they calculate a ratio comparing the monthly rental income of the property to its total monthly debt obligations.
If the property generates enough rent to cover the principal, interest, taxes, and insurance, the loan is generally approved. This product is incredibly advantageous for self-employed investors or those who have reached the borrowing limits of conventional banks. It allows investors to scale their portfolios infinitely, provided each new asset cash flows positively.
Hard Money and Private Capital
When speed and flexibility are paramount, hard money loans provide an aggressive solution. Traditional banking institutions can take up to sixty days to close a transaction. In a competitive market like East Los Angeles, waiting two months often means losing a lucrative deal to an all-cash buyer.
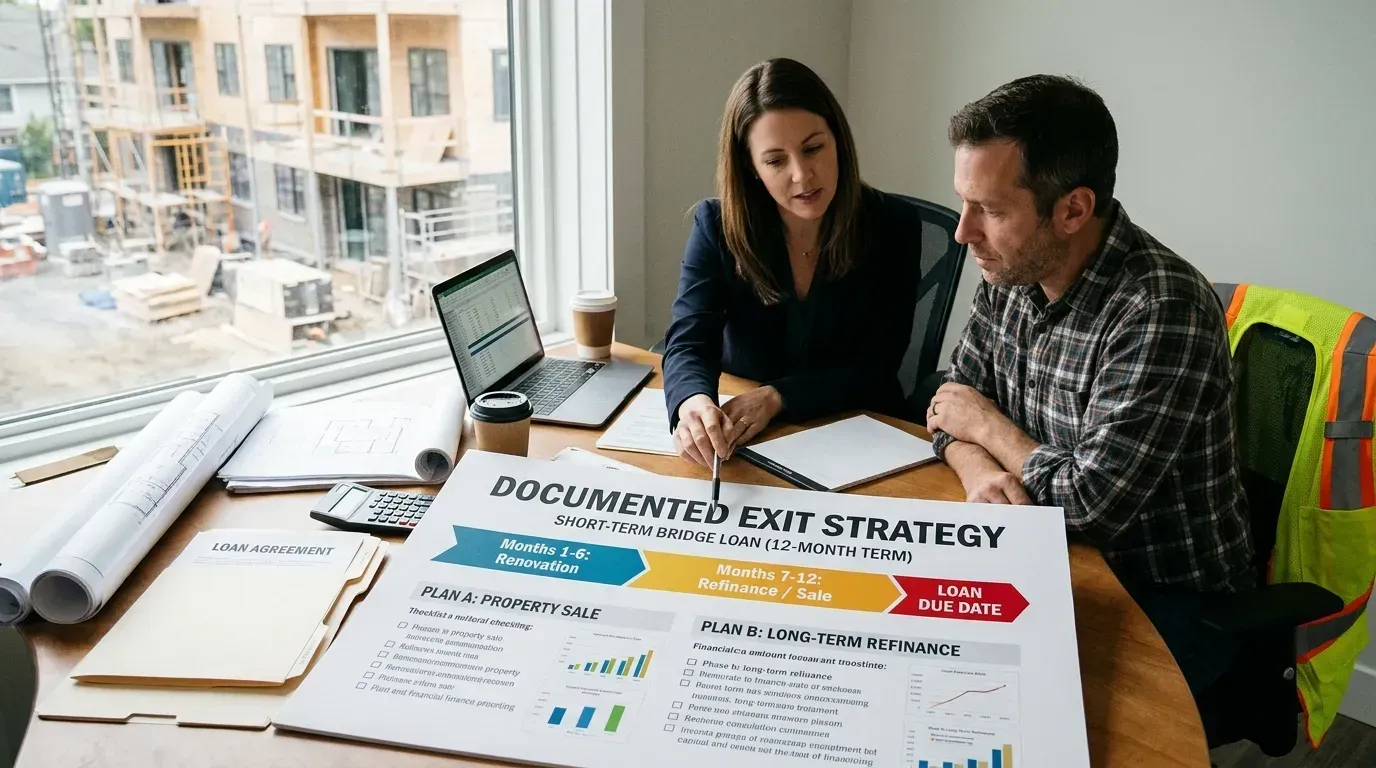
Hard money lenders focus strictly on the physical value of the real estate. If you locate a distressed property at a significant discount, a hard money loan allows you to fund the acquisition and the necessary renovations simultaneously. Once the property is rehabilitated and stabilized with reliable tenants, the investor can refinance the short-term hard money loan into a long-term, fixed-rate mortgage.
Commercial Real Estate Financing
For investors looking to acquire larger assets, such as apartment buildings with five or more units, specialized financing is required. Residential loans max out at four units. Beyond that threshold, the asset transitions into the commercial space. Securing commercial real estate loans involves a rigorous analysis of the net operating income and the capitalization rate of the building.
Commercial lenders look closely at rent rolls, trailing twelve-month expense reports, and the professional management structure in place. These loans often feature different amortization schedules, sometimes offering interest-only periods followed by a balloon payment. This structure allows syndicators and large-scale operators to maximize their cash-on-cash returns during the hold period.
Strategic Leverage and Asset Refinancing
Acquisition is only the first phase of real estate investing. True wealth generation occurs when investors actively manage their equity. As a property appreciates over time and the principal balance of the loan decreases, trapped equity begins to accumulate. Savvy investors do not let this capital sit idle.
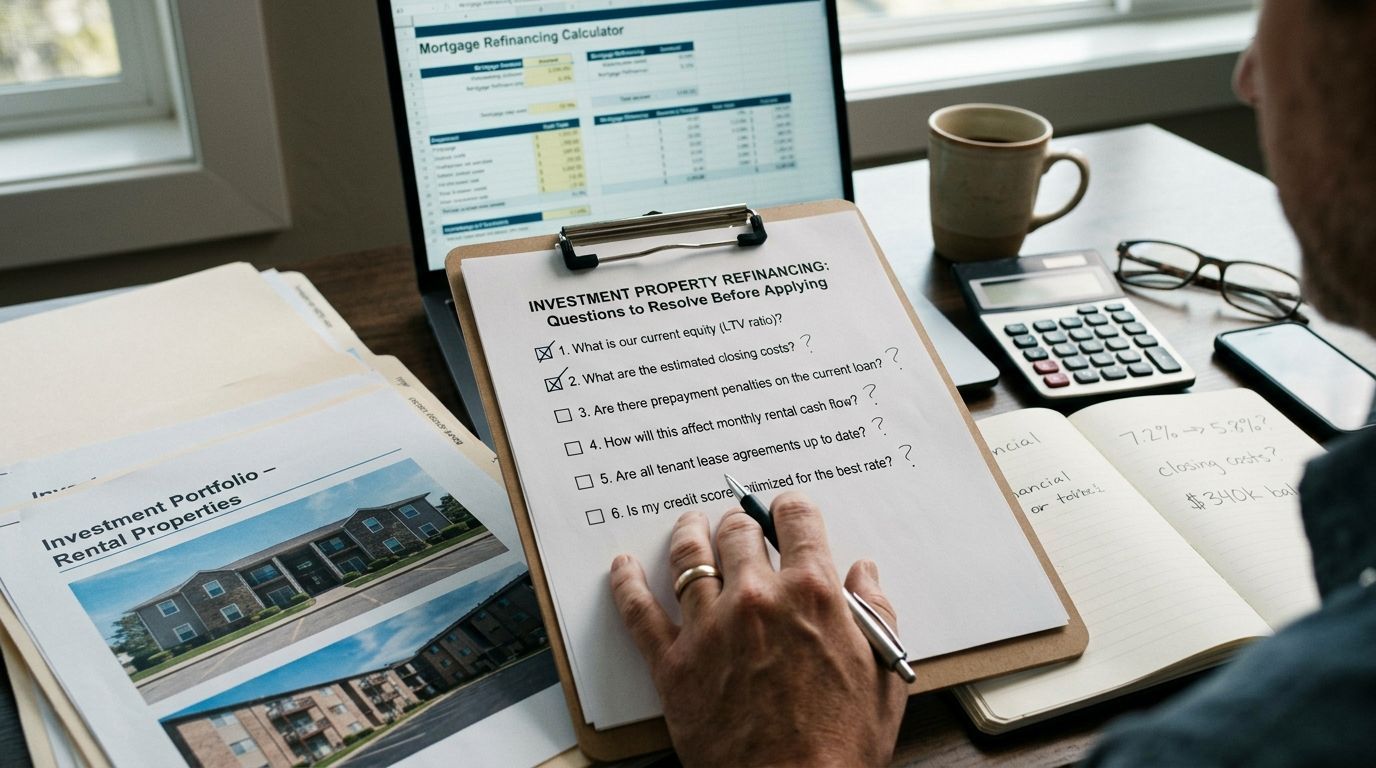
Through a cash-out refinance, you can extract a portion of that accumulated equity and deploy it as a down payment on a subsequent property. This strategy allows a single initial investment to snowball into a multi-property portfolio. Executing this maneuver requires a precise understanding of property valuation and current interest rate environments. For an in-depth look at how to optimize this process locally, we highly recommend reviewing our guide on strategic property refinancing.
Refinancing also serves as a vital tool for improving cash flow. If market conditions shift favorably, replacing an older, high-interest loan with a modernized debt structure immediately decreases monthly expenses. This expands the profit margin of the asset without requiring any physical improvements to the property itself.
Key Qualifications for Real Estate Investors
While investment loans prioritize the performance of the asset, lenders still require borrowers to demonstrate baseline financial responsibility. Preparing your financial profile in advance significantly streamlines the underwriting process.
Lenders typically review the following core components:
- Credit Profile: A strong credit score demonstrates historical reliability. While asset-based lenders are more forgiving than conventional banks, a solid credit history ensures access to the most competitive interest rates and terms.
- Liquid Reserves: Institutional lenders want assurance that the borrower can weather unexpected vacancies or major repairs. Having three to six months of mortgage payments available in a liquid account is a standard requirement.
- Real Estate Experience: For highly specialized loans like renovation or commercial products, lenders may look at your track record. Having a history of successful property management or rehabilitation projects increases your credibility and borrowing capacity.
- Clear Title and Entity Formation: Many investors choose to close loans under a Limited Liability Company to protect their personal assets. Ensuring your corporate entities are in good standing and the property title is free of major encumbrances is critical for a smooth closing.
Partnering with a Local Lending Expert
Real estate is inherently local. Macro-economic data rarely reflects the street-level realities of a specific neighborhood. Working with a national lender located thousands of miles away often introduces unnecessary friction. Out-of-state underwriters may not understand the specific zoning laws, neighborhood boundaries, or rent control ordinances unique to Southern California.
Partnering with a lender based in East Los Angeles provides a distinct competitive advantage. A local partner can expedite appraisals, accurately underwrite market rents, and provide insights that only come from operating in the immediate geography. We specialize in structuring capital that fits the precise needs of local properties and local investors.
If you are currently evaluating an acquisition or looking to restructure the debt on your existing portfolio, we encourage you to reach out to our team. Direct communication allows us to review your specific scenario, analyze the property data, and outline a customized funding roadmap.
Frequently Asked Questions
What is the minimum down payment required for an investment property loan?
Most rental property loans require a minimum down payment of twenty to twenty-five percent. This equity requirement provides a safety net for the lender and ensures the borrower has a vested interest in the success of the asset. Highly qualified borrowers utilizing specific DSCR products may occasionally secure slightly higher leverage, but twenty percent remains the industry standard baseline.
How do lenders calculate the Debt Service Coverage Ratio?
Lenders calculate the DSCR by dividing the gross monthly rental income of the property by the total monthly debt service. The debt service includes the principal, interest, property taxes, insurance, and any applicable Homeowners Association fees. A ratio of 1.0 means the rent exactly covers the debt. Most lenders require a minimum DSCR of 1.20 to ensure the property generates sufficient positive cash flow to absorb minor vacancies or maintenance costs.
Can I finance a multi-family property using a standard rental loan?
Yes, standard rental property loans can be used to finance multi-family properties that have up to four residential units. These are classified as residential real estate. If the property contains five or more units, it is classified as commercial real estate. Financing a five-unit or larger building requires a specialized commercial mortgage, which involves different underwriting standards focused heavily on the net operating income of the entire complex.