Supercharge Your Real Estate Investing: Why Pre-Approval is Your Secret Weapon
In the fast-paced world of real estate investing, especially in a competitive arena like Los Angeles, hesitation is the enemy of profit. You’ve spent weeks hunting, you’ve analyzed dozens of deals, and you’ve finally found it: the perfect property. It has great bones, it’s in an up-and-coming neighborhood, and the numbers work. But while you’re scrambling to get your financing in order, another, more prepared investor swoops in with a clean offer and closes the deal. You’ve just been outmaneuvered.
This frustrating scenario is all too common, and it almost always boils down to one critical factor: financing readiness. The single most powerful tool an investor can wield to prevent this is not just cash, but the next best thing—a loan pre-approval. Getting pre-approved isn't just a bureaucratic hoop to jump through; it's a strategic move that transforms you from a casual browser into a serious contender. It’s the key to unlocking speed, credibility, and negotiating power. Here at GRO Los Angeles Hard Money Real Estate, we’ve seen countless deals won or lost based on this single step.
This comprehensive guide will break down why pre-approval is non-negotiable for the modern real estate investor, how it works, and how it gives you a decisive edge in any market.
What Exactly is Pre-Approval (And What It Isn't)?
Before we dive into the strategic advantages, it's crucial to understand what pre-approval truly is. Many investors mistakenly use the terms "pre-qualification" and "pre-approval" interchangeably, but they represent vastly different levels of financial verification and carry different weight with sellers.
Pre-Qualification vs. Pre-Approval: The Critical Difference
A pre-qualification is a preliminary, informal estimate of how much you might be able to borrow. It's typically based on self-reported financial information—your stated income, assets, and debts. There is no credit check and no verification of your documents. It’s a useful first step to get a ballpark figure, but it holds almost no weight in a competitive offer situation.
A pre-approval, on the other hand, is a conditional commitment from a lender to provide you with a loan up to a certain amount. This is a much more rigorous process. The lender will verify your financial information by pulling your credit report and requiring you to submit documentation, such as:
- Tax returns (personal and business)
- Pay stubs or proof of income
- Bank statements and investment account statements
- Business entity documents (if applicable)
- A detailed list of your assets and debts
Once the lender has underwritten this information, they issue a formal pre-approval letter. This letter is your golden ticket, signaling to sellers and agents that you are a financially vetted, serious buyer.
| Feature | Pre-Qualification | Pre-Approval |
|---|---|---|
| Process | Informal, based on self-reported data. | Formal application with document verification. |
| Credit Check | No (or only a soft pull). | Yes, a hard credit inquiry is required. |
| Verification | None. Information is not verified. | Income, assets, and debts are verified. |
| Lender Commitment | None. It's an estimate. | Conditional commitment to lend. |
| Impact on Offer | Minimal. Shows initial interest. | Significant. Shows you are a serious, capable buyer. |
The 4 Core Advantages of Pre-Approval for Real Estate Investors
With a pre-approval letter in hand, you’re no longer just window shopping. You are an empowered investor ready to act decisively. Here’s how this single document supercharges your investment strategy.
1. Unshakeable Credibility and Negotiating Power
Imagine a seller receives two similar offers. One comes from an investor who says they are "confident" they can get a loan. The other comes with a pre-approval letter from a reputable lender. Who do you think the seller will take more seriously? The pre-approved buyer, every time. A pre-approval letter demonstrates that you have already done the financial legwork. It removes a major element of uncertainty for the seller, making your offer stronger, safer, and more attractive—even if it isn't the highest bid. This credibility can give you leverage in negotiations on other terms, like inspection periods or closing dates.
2. Unmatched Speed and Agility
The best investment deals don't wait around. In markets like Los Angeles, properties can go under contract within days, or even hours, of being listed. Without a pre-approval, you are always one step behind. The time it takes to gather documents and wait for a lender to review your file is time you don't have. With a pre-approval, you can make an offer the moment you find the right property. This ability to move quickly is often the single most important factor in securing off-market deals or winning in a multiple-offer situation.
3. Crystal-Clear Budgeting and Focus
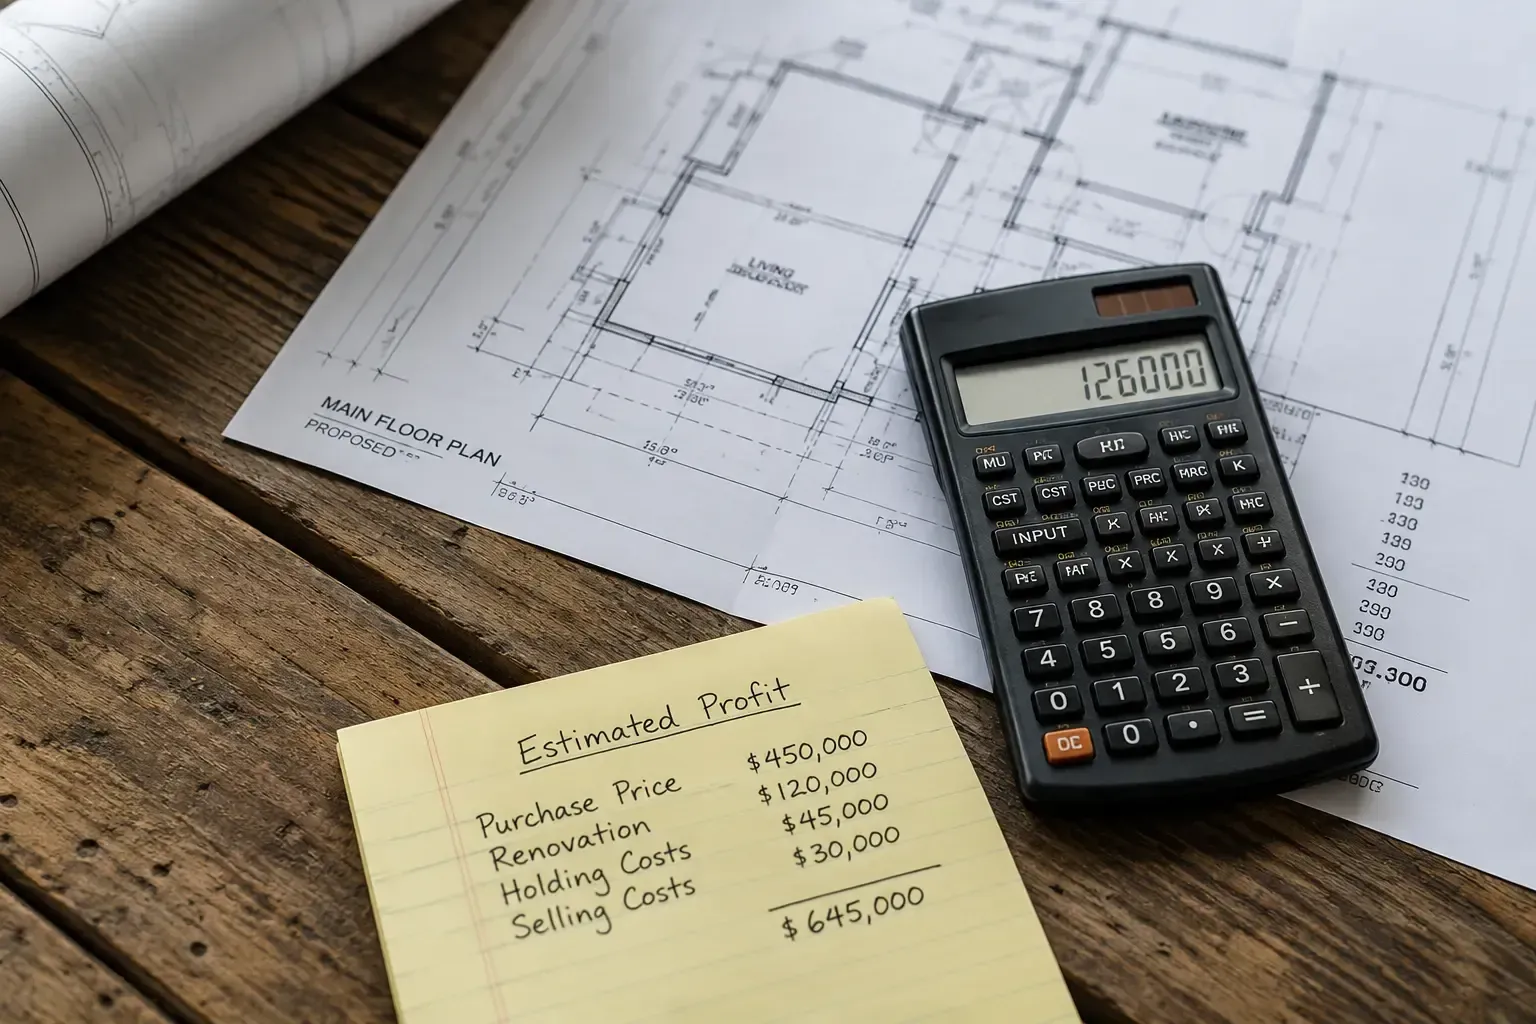
Real estate investing is a numbers game. Wasting time analyzing properties that are outside your financial reach is inefficient and demoralizing. The pre-approval process forces you to get a crystal-clear understanding of your purchasing power. You'll know your exact loan amount, potential interest rate, and estimated monthly payments. This allows you to filter your property search with laser focus, confidently analyze deals within your budget, and accurately project your potential return on investment (ROI). It removes the guesswork and replaces it with data-driven decision-making.
4. A Smoother, Faster Closing Process
Because most of the financial underwriting is completed during the pre-approval stage, the journey from contract to closing is significantly streamlined. The lender has already reviewed your financial health, so there are fewer opportunities for last-minute surprises or delays. While the specific property will still need to be appraised and approved, your side of the financial equation is largely settled. This leads to a faster, more predictable closing, which is a major benefit for both you and the seller.
The Hard Money Advantage: Pre-Approval for Serious Investors
For real estate investors, particularly those focused on fix-and-flip or BRRRR strategies, traditional bank loans can be slow and restrictive. This is where alternative financing, like hard money loans, becomes essential. Getting pre-approved for a hard money loan is a game-changer.
At GRO Los Angeles Hard Money Real Estate, our lending decisions are based primarily on the value of the real estate asset, not just your personal income or credit score. This asset-based approach means our pre-approval process can be significantly faster and more flexible. Our team's deep experience in the investment world, which you can learn more about on our About Us page, allows us to understand the unique needs of investors. Our range of financing services are specifically designed to provide the speed and agility required to succeed in competitive markets.
A pre-approval from a respected hard money lender signals to sellers that you have access to fast, reliable capital and are capable of closing quickly—often in a matter of days, not weeks or months.
Your Step-by-Step Guide to Getting Pre-Approved
Ready to gain your competitive edge? Here’s a straightforward guide to the pre-approval process.
- Organize Your Financial Documents: Be prepared. Gather at least two years of tax returns, two months of bank statements, recent pay stubs, and documents for any business entities you own. The more organized you are, the smoother the process will be.
- Check Your Credit: Know your credit score and review your report for any errors. While hard money lenders are more flexible on credit, a better score can still lead to more favorable terms.
- Define Your Investment Thesis: Have a clear idea of what you’re looking for. Are you flipping single-family homes? Buying a small multi-family rental? Knowing your strategy helps the lender tailor the pre-approval to your specific needs.
- Choose the Right Lender: Research lenders that specialize in investment properties. A traditional mortgage broker may not understand the urgency and creative financing investors need. A specialist like GRO Los Angeles Hard Money Real Estate understands the game.
- Submit Your Application: Complete the lender's application fully and honestly. Provide all requested documentation promptly to keep the process moving.
Conclusion: Stop Wishing, Start Winning
In the high-stakes game of real estate investing, you need every advantage you can get. A loan pre-approval is far more than a piece of paper; it’s a declaration that you are a serious, prepared, and powerful player in the market. It grants you the credibility to be taken seriously, the speed to seize opportunities, and the confidence to make bold, calculated moves.
Don't let another perfect deal slip through your fingers due to financing delays. Take the proactive step to get pre-approved and transform your investment approach from reactive to dominant. Ready to supercharge your real estate investing journey? Contact our team today to begin your pre-approval process and position yourself for success.
Frequently Asked Questions
What is the difference between pre-approval for an investment property versus a primary residence?
Lenders typically have stricter requirements for investment properties. They may require a larger down payment (often 20-25%), a higher credit score, and proof of cash reserves to cover several months of mortgage payments. This is because investment properties are considered higher risk than primary residences.
How long does a pre-approval letter last?
Most pre-approval letters are valid for 60 to 90 days. This is because your financial situation (income, debt, credit score) can change. If you don't find a property within that timeframe, you'll likely need to update your information with the lender to get a new letter.
Does getting pre-approved negatively affect my credit score?
Yes, the pre-approval process involves a "hard inquiry" on your credit report, which can cause a temporary, small dip in your credit score (usually less than five points). However, the strategic advantage of being pre-approved far outweighs this minor impact. Multiple inquiries from the same type of lender within a short period (usually 14-45 days) are often treated as a single inquiry to allow you to shop for the best rates.
Can I get pre-approved with a hard money lender like GRO Los Angeles Hard Money Real Estate if my credit isn't perfect?
Yes. One of the key advantages of hard money lenders is their flexibility. Since the loan is primarily secured by the property's value (the "hard asset"), lenders are often more lenient on credit scores and income history compared to traditional banks. The strength of the deal is the most important factor.